
The short answer: you can compare several mortgage lenders without piling up damage to your credit. According to the Consumer Financial Protection Bureau, multiple credit checks from mortgage lenders within a 45-day window are recorded on your credit report as a single inquiry. So gather your documents first, then do all of your lender conversations inside that window, and ask each lender for a written pre-approval and a quote you can compare side by side.
If you are just starting, start your pre-approval questions here or book a short call with me. I will help you understand what a seller will want to see.
Why pre-approval comes before the house hunt
Falling for a home before you know your budget is one of the most painful ways to start. A pre-approval tells you, and the seller, roughly what a lender is willing to lend once it has looked at your income, assets and credit. In a competitive Twin Cities market, many sellers will not seriously consider an offer without one.
Pre-qualification vs. pre-approval
Here is something most buyers never hear: lenders use these two words differently. The CFPB notes that some lenders “prequalify” you from what you tell them, without verifying it, and only “pre-approve” you after they check your documents. Others issue a stronger written commitment. Ask your lender exactly what they verified. The more they have verified, the more weight your letter carries.
One more thing to know: a pre-approval is not a guaranteed loan. It is a strong signal, not a promise. Your final approval still depends on the home, the appraisal and your finances staying steady until closing.
Gather these before you call anyone
- Recent pay stubs and the last two years of W-2s or tax returns (self-employed buyers usually need more)
- Recent bank and investment statements
- A photo ID and your Social Security number for the credit check
- Details on any other debts, child support or alimony
- Gift letters, if family is helping with your down payment
Protect your credit while you shop
- Keep lender shopping inside 45 days so the mortgage checks count as one inquiry, per the CFPB.
- Do not open new credit such as a car loan, store card or furniture financing until after closing.
- Do not move large sums around without a paper trail. Lenders will ask where deposits came from.
- Keep paying everything on time. A late payment between pre-approval and closing can change your loan.
How I help
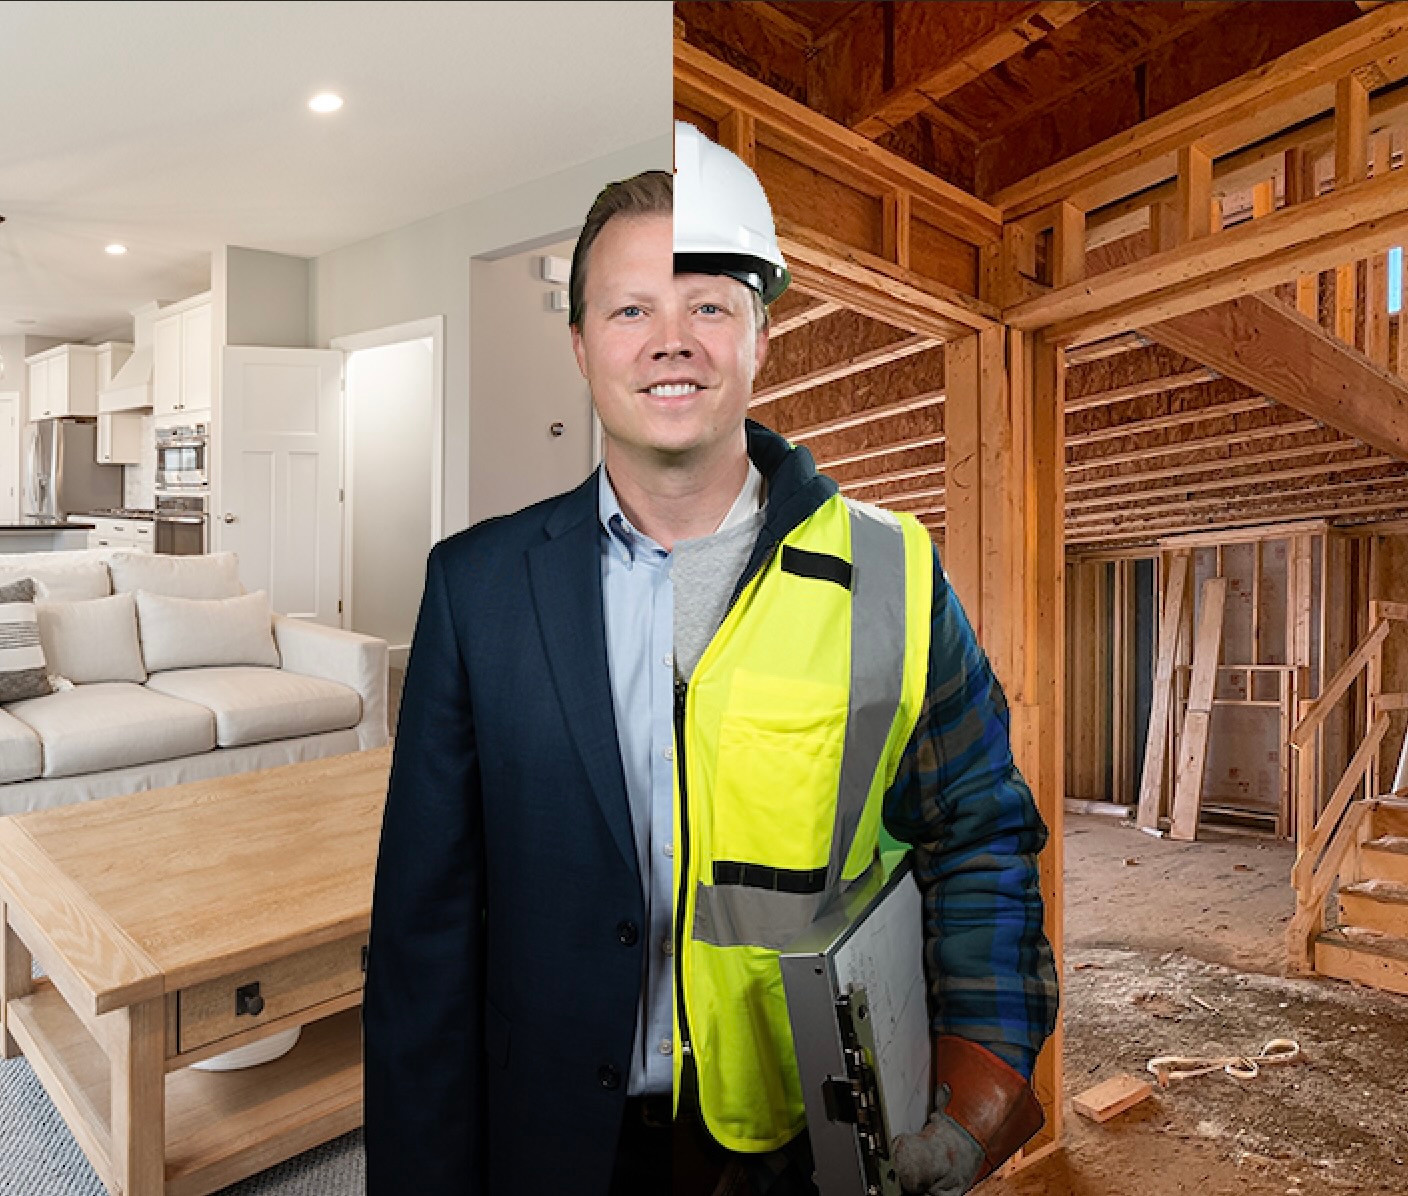
I have spent more than twenty years on both sides of the closing table, and as a builder too. I can tell you what the letter in your hand means to a seller, and when it is worth asking your lender for something stronger before you write an offer. Want to see what homes in your price range have sold for? Explore my sold homes map.
Quick answers
Does shopping for a mortgage hurt my credit score?
According to the CFPB, multiple credit checks from mortgage lenders within a 45-day window are recorded as a single inquiry, so you can compare lenders inside that window.
Is a pre-approval a guaranteed loan?
No. The CFPB describes pre-approval letters as not guaranteed loan offers. Final approval still depends on the home, the appraisal and your finances at closing.
What is the difference between pre-qualification and pre-approval?
Lenders use the terms differently. Some pre-qualify you from information you report without verifying it and pre-approve you only after checking your documents. Ask your lender what they verified.
Ready to take the first step? Start your pre-approval questions, or call or text me at 952-314-9446.
Please note: I don’t handle rentals or property management. I work with sellers and buyers, and that’s where I can help you most.
Stay close to the market, without the noise.
Every so often I send a short, practical note: what Twin Cities homes did, prep tips that are worth the money, and neighborhoods worth a look. Sign up and you’ll also get this guide as a PDF to keep.

Thank you! You’re on the list.
I’m glad you’re here. Your PDF copy of this guide is ready below, and a quick confirmation is on its way to your inbox. Whenever you want to talk about your own home or a move, I’m a call or text away.
Ready to find the right home?
Tell me what you’re looking for and I’ll send homes that truly fit, then guide you through offers, inspections and closing.
Call/Text David Olson: 952-314-9446
david@twincitiespropertyfinder.com · DavidOlsonRealEstate.com